
All Around Texas Roofing documents storm damage for insurance claims across Frisco, McKinney, Prosper, Celina, Anna, Melissa, Aubrey and the surrounding Collin and Denton County communities.
We inspect before a claim exists, photograph and scope the damage to a standard an adjuster can work from, meet your adjuster on the roof, and support a supplement when the tear off reveals more. What we do not do is file or negotiate your claim, because Texas law does not allow a contractor to do that.
Call (469) 598-0899 for a free roof inspection and written documentation before you file.
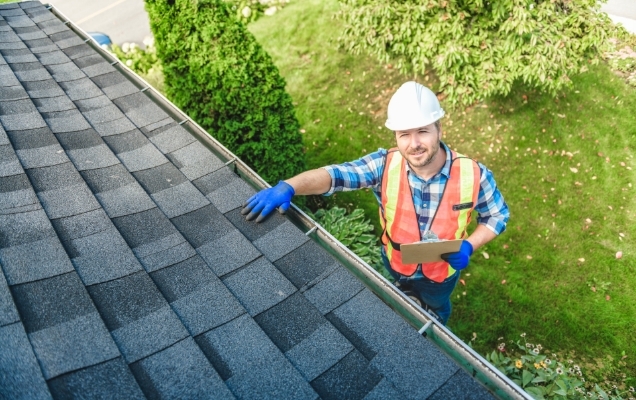
What we do:
What we will not do: file your claim, negotiate it on your behalf, touch your deductible, tell you what your policy covers, or manufacture damage to create a claim. If an inspection involves aggressive tab lifting, scraping or a tool applied to a shingle you did not agree to, walk them off the property.
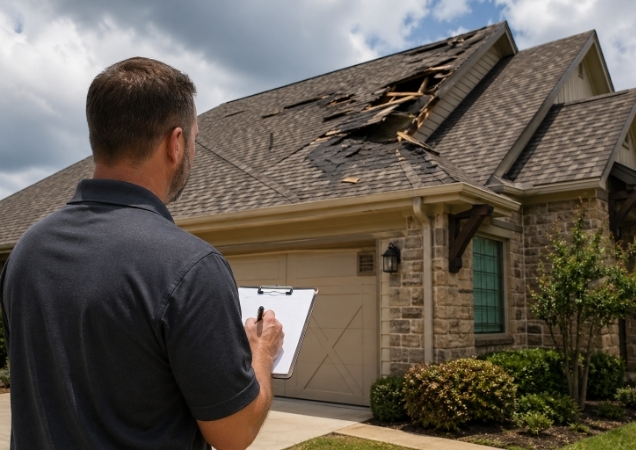
before a claim exists. You get photographs and a written assessment either way.
using the documentation we hand you.
and schedules an inspection.
with our photographs and test squares.
We read it against ours and identify exactly what is missing.
with permits pulled where the jurisdiction requires them.
photographed at the time of discovery.
On a replacement cost policy the carrier usually pays in two parts. The first is the actual cash value, which is the cost of the work minus depreciation and minus your deductible. The rest, the recoverable depreciation, is held back and released after the work is done and the cost is proven.
Texas Insurance Code section 707.004 lets the insurer refuse to release that holdback until it receives reasonable proof that you paid your deductible. The statute names what counts: a canceled check, a money order receipt, a credit card statement, or a copy of an executed installment plan contract.
Two consequences. Keep the proof that you paid your deductible, because you are likely to be asked for it. And understand why a contractor who “absorbs” your deductible creates a problem that lands on you: there is no proof of payment to produce, and the holdback is the carrier’s to withhold.
On an actual cash value policy there is no second payment. Which type you hold is in your policy document. If you want the damage documented properly before you file, get your free estimate .
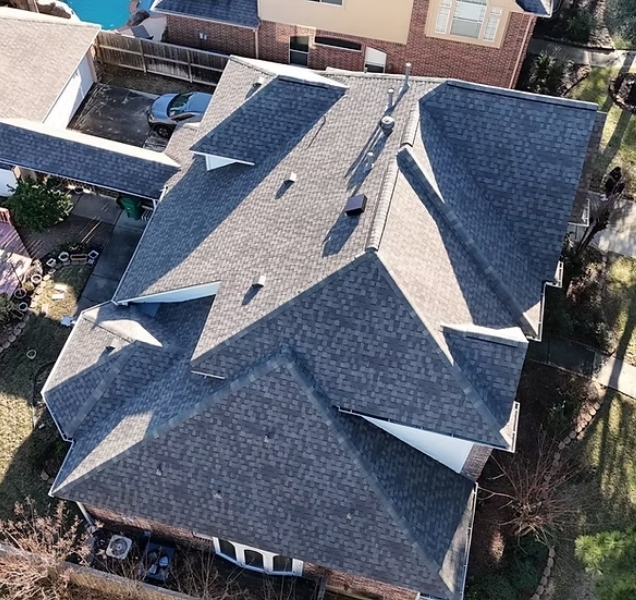

Not through bad faith, usually. An adjuster works through a backlog after a storm and writes what the evidence supports. These are the items that most often go missing, and every one would have been settled by a photograph.
| Commonly missed | Why it goes missing |
|---|---|
| Soffit and fascia | Nobody looks along the eave line, and damage there reads as age |
| Window screens and seals | Screens get waved off, seal failure is invisible until it fogs |
| Gutter and downspout dents | Assumed cosmetic, though the same impacts hit the roof |
| Fences and patio covers | They sit under a different coverage part and are easy to overlook |
| Skylights | Elevated, awkward to inspect, and a failed seal may not leak for weeks |
| Siding away from the street | The side that faced the storm is often not the side photographed |
| Decking | Genuinely cannot be seen until the roof is off, which is what supplements are for |

We inspect before you file, so you know whether a claim is worth making.
Documentation built for review, not a phone call describing something nobody photographed.

We attend the adjuster's inspection rather than sending a report and hoping.

We will not touch your deductible, and we will tell you why anyone offering to is a problem.
We will read another contractor's paperwork with you at no charge, including anything you have already signed.
One contractor for the whole exterior, so the claim reflects the storm rather than only the roof.
We document storm damage claims across:
Our office is on Preston Road in Frisco.
If a storm has just been through and your roof is open, start with emergency tarping . Most Texas policies require you to take reasonable steps to prevent further damage, and that work is normally scoped as its own line on the claim.
 4.9★ Rating from 1,235+ Texas Roofing Customers

Yes. Texas Insurance Code section 707.002 requires the insured to pay any deductible applicable to a first party claim. A contractor who offers to pay, waive or absorb it commits an offense under Business and Commerce Code section 27.02, and so does any arrangement that assists you in avoiding it.
No. Texas Insurance Code section 4102.163 prohibits a contractor from acting as a public adjuster for any property where it is providing contracting services, even if you sign a power of attorney. What a contractor can do is inspect, document, scope, attend the adjuster’s inspection and support a supplement with evidence.
Get the inspection first. It tells you whether there is qualifying damage, and a claim filed on an undamaged roof still becomes part of your claims history. The inspection is free and the report is yours either way.
On a replacement cost policy the carrier typically pays actual cash value first and holds back depreciation, releasing it once the work is complete and proven. Section 707.004 allows the insurer to hold that release until it has reasonable proof you paid your deductible, and names a canceled check, money order receipt, credit card statement or executed installment plan as acceptable proof.
That depends on your carrier, your policy and your claims history, and no roofer can answer it. Your agent can. It is a reasonable question to ask before filing rather than after.
Policies set their own deadlines and they differ, so read yours rather than relying on a contractor’s summary. What is consistent is that waiting makes it harder to attribute damage to a particular storm.
That is common and it is a documented conversation rather than an argument. We compare the returned scope against our photographs and test square counts and identify exactly what is missing and where. Evidence moves scopes; opinions do not.
One, in almost every case. Damage from a single storm belongs on one claim against one deductible. Splitting it across contractors months apart is how the second half quietly becomes your own expense.
Read what you signed, particularly any clause assigning your claim benefits or binding you to whatever the carrier approves. Bring it and the roof paperwork and we will look at both with you at no charge.
The inspection decides everything after it. Photographs, marked test squares, a written scope, and a straight answer about whether you have a claim worth filing.
Call (469) 598-0899 or request your free inspection.
© Copyrighted 2026 All Around Texas Roofing. All Rights Reserved. Powered by Fast Hippo Media.
 info@allaroundtexasroofing.com
 Schedule Now
 (469) 598-0899
